Why Your “Foreign” Income Might Be Portuguese in the Eyes of Portuguese Tax Authorities
Francisca Abrantes | Tax Consultant
In today’s globalized and remote work environment, the line between “foreign” and “domestic” income has become increasingly blurred. Even if you earn from clients abroad, the Portuguese Tax Authority may still consider your income Portuguese under Article 18 of the CIRS. This article explores the risks for digital nomads and international professionals, highlighting why careful tax planning and expert guidance are essential to avoid unexpected liabilities and maximize available exemptions.
Foreign Income in Portugal: What Expats and Digital Nomads Must Know
The Digital Nomad & Global Professional Dilemma
In an era of remote work and global consultancies, the lines between "here" and "there" have blurred. You live in Portugal, your client is in New York, and the bank account is in London. Naturally, you might think: "This is foreign income".
However, the Portuguese Tax Authority (AT) has a different lens. They don’t just follow the money; they follow the person - you.
The purpose of this briefing is to highlight a specific technical risk -
Article 18 of the CIRS - and why navigating this year’s tax return requires more than just a calculator; it requires a
defensive strategy.
The "Article 18" Reality Check
Article 18 is the "GPS" of the Portuguese tax system. It determines whether income is "obtained in Portuguese territory." If the AT clicks "Yes" on Article 18, your "foreign" income is suddenly "domestic".
Why does this happen?
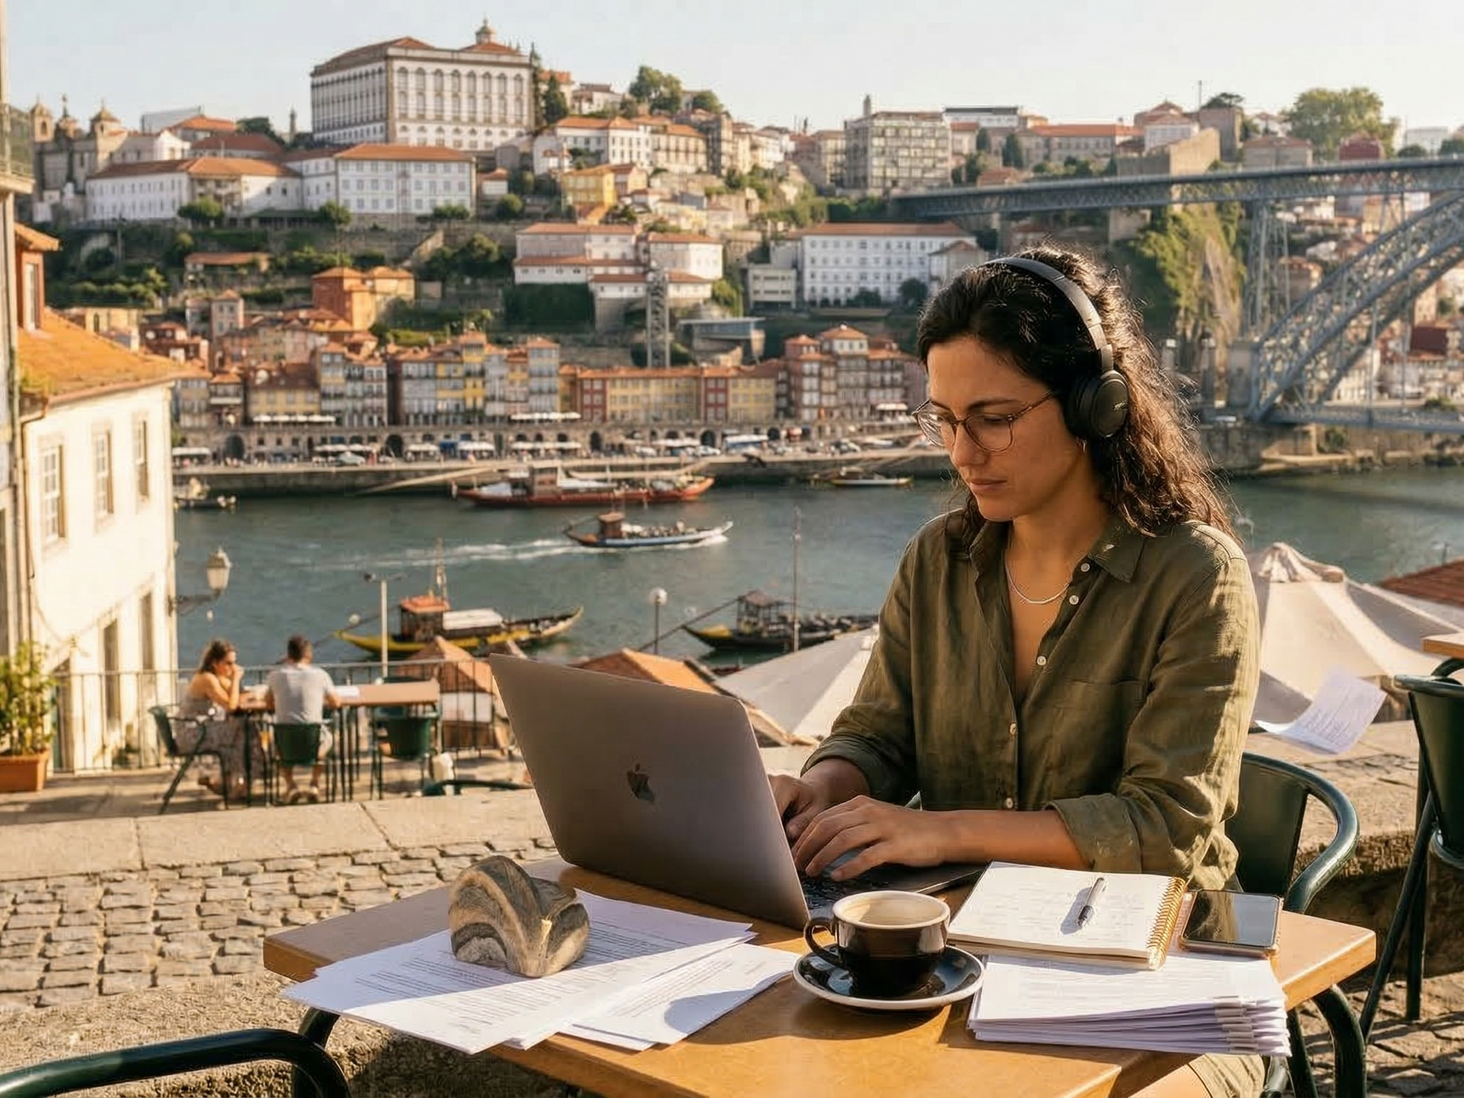
Article 18(1) determines whether income is "obtained in Portuguese territory". The AT’s interpretation is increasingly strict: if you are sitting in a home office in Lisbon or a café in Porto while performing a service, the law argues that the source of that wealth is your physical presence in Portugal.
Even if the entity paying you has no presence in Portugal, the mere fact that the activity was exercised here is enough for the AT to claim its piece of the pie.
The Stakes: It’s Not Just About a Different Form
You might ask, "What’s the big deal if it’s called Portuguese or Foreign, as long as I pay tax?" The difference, in reality, can be worth thousands of Euros.
The NHR (Non-Habitual Resident) Vulnerability
For those under the NHR regime, the "Exemption Method" is the Holy Grail. Foreign income may be exempt in Portugal if certain conditions are met in the source country. However, If the AT invokes Article 18 and reclassifies your income as "Portuguese Source," you lose that exemption. You could go from paying 0% or a flat 20% to the standard progressive scales that reach up to 48% (plus solidarity surcharges).
The Double Taxation Ghost
If Portugal claims the income is domestic and the other country also claims it (because the payer is there), you are stuck in a bureaucratic minefield. Avoiding double taxation requires precise reporting and a deep understanding of International Double Taxation Agreements (DTAs). One wrong box on your Tax Return, and you are paying two governments for the same hour of work.
Conclusion: Let the Experts Handle the Heat
At LVP Advogados, we believe that preparing a tax return is a defensive exercise. The Portuguese Tax Authority is becoming increasingly digital and aggressive in its "automatic cross-checking". They are looking for inconsistencies between what foreign entities report and what you declare here.
Our role is to look beyond the surface. We analyze the substance over form-checking how international treaties (DTAs) interact with Article 18 to find the most secure path for your specific case. We want to ensure that your global professional success doesn't get tangled in local red tape.
As we prepare for the upcoming Tax Season, our message is simple: don't leave your financial peace of mind to chance. The risk of Article 18 is real, but it is manageable with the right approach.
Should you require our support or a detailed analysis of your tax situation, please feel free to reach out to us through our contact form.